“I used to think that if there was reincarnation, I wanted to come back as the president or the pope. But now I want to come back as the bond market. You can intimidate everybody.” (James Carville, 1993)
James Carville’s three-decade-old quote about the bond market’s intimidating power has never felt more relevant. Since mid-August, bond market investors have been reasserting themselves as the ultimate arbiters of fiscal discipline, and the US government is feeling their wrath.
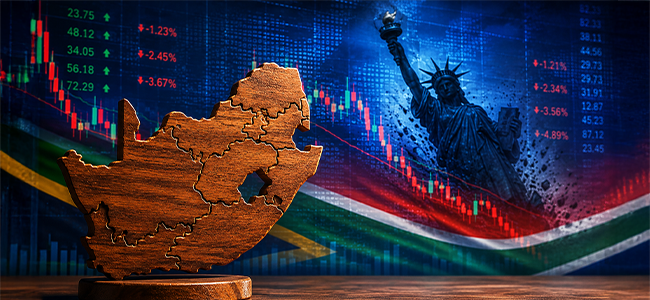
The 30-year US Treasury yield reached 5.34% on 18 August, its highest level since 2007. The 10-year yield followed at around 4.74%. This shows investors are demanding greater compensation for holding US government debt, as a historically large deficit, persistent inflation and a fresh wave of AI-linked corporate bond issuances compete for the same pool of capital.
Bond vigilantes, reawakened
The US Treasury Department reacted quickly. On 19 August, Secretary Scott Bessent doubled the department’s bond buybacks, from $2 billion to at least $4 billion, targeting longer-dated debt to steady the market. Yields eased only slightly, highlighting that the underlying drivers are structural:
- US debt issuance is rising faster than natural demand can absorb it.
- US inflation has stayed above target for five consecutive years.
- Corporate borrowing to fund the AI buildout is now competing directly with sovereign debt for investor capital.
The sell-off wasn’t confined to the US: Germany, France, Japan and the UK experienced it too, confirming an old market adage that when the US sneezes, the rest of the world catches a cold.
Why South Africa hasn’t followed the script
A risk-off shift of this scale would typically push South African yields higher too, but the opposite happened. Its 10-year yield has fallen to around 8.5%, the rand has strengthened to roughly R16.00 to the dollar, its best level since February, and foreign investors bought a net R23.1 billion of local government debt in the first week of August alone. The dollar-funded rand carry trade returned 2.5% to 3.5% this month, the best of 22 emerging-market currencies tracked by Bloomberg. SA’s 7% repo rate, improving current account and fading geopolitical risk premium are driving this foreign interest.
What this means for portfolios
While SA benefited in August, history shows the tide can turn just as quickly. The truth is:
- Carry-trade inflows are not evidence of a structural re-rating, and can reverse quickly.
- A renewed US fiscal scare or Fed hawkishness would erode the rand’s advantage.
- Domestic credibility matters, and the SA Reserve Bank’s decision to hold interest rates in July dented it.
With this in mind, treat this month’s market tailwinds as a windfall rather than as a decoupling from the US bond market woes.
*All facts and figures accurate at time of writing.
Jason Yutar: +27 83 415 9603 or
Zaheera Mohammed: +27 82 775 1898
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews